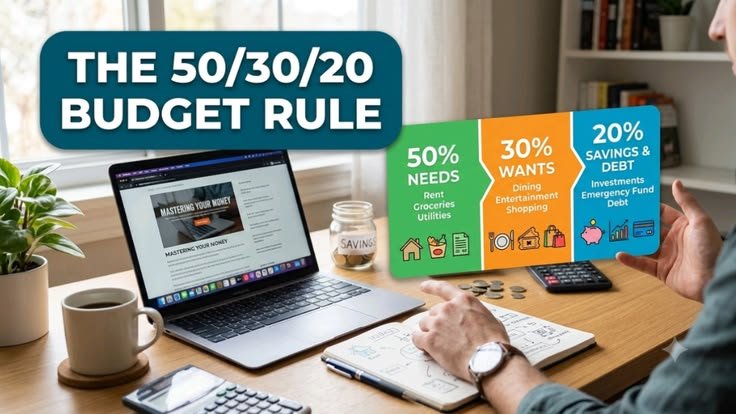
The 50/30/20 rule is a simple budgeting method that divides your monthly income into three parts, needs 50%, wants 30% and savings 20%. Managing money sounds simple until monthly expenses, EMIs, rent, groceries, lifestyle spending and unexpected costs start competing for the same salary. This is where the 50/30/20 budget rule becomes popular. The idea is straightforward: spend 50% percent of your income on needs, 30% on your wants and 20% of your income goes to saving and investments. It offers a simple framework for people who want better control over their finances without tracking every single rupee. For many Indians, the answer depends on the income, city, family responsibilities, debt, and lifestyle and many more. people living in big Metro cities Mumbai, Delhi, Bengaluru and Hyderabad spend larger money on rent, while a person living with family may be able to save more than 20%. Rising living costs, education expenses, medical bills, and EMIs can also make the standard formula difficult to follow.
The idea is simple:
-
- 50% of your income goes into your Needs
-
- 30% of your income goes into Wants
-
- 20% of your income goes into savings and financial goals
But there is an important question for Indian households: Does the 50/30/20 rule actually work in India?
The answer is: It can be a useful starting point, but it should not be treated as a fixed formula.
Indian households have very different income levels, rent costs, family responsibilities, loan obligations and financial goals. Therefore, the right budget for one person may not work for another.
Let’s understand the rule and how you can adapt it to an Indian lifestyle.
What Is the 50/30/20 Rule?
Needs 50%
The first 50% which is also the half of your hard-earn monthly salary or income goes in into your basic necessity or needs like rent, groceries, food, utility bills, transport and so on.
If your monthly take-home income or salary is 50,000 rupees then 50% which is also half of your salary which is 25,000 rupees goes into your basic needs like:
-
- Rent
-
- Groceries
-
- Electricity
-
- Transport
-
- Water bills
-
- Education expense
-
- Life insurance premium
-
- Loan and debt payment or EMI’s
-
- Health insurance
-
- Medical checkups
Wants 30%
This portion 30% of your monthly income goes into your wants like shopping, travelling ,dinning-out, subscription and entertainment.
The next 30% of 50,000 rupees which is 15,000 rupees is for things that improve your lifestyle but not essential for survival like:
-
- Travelling
-
- eating at restaurants
-
- movies and entertainment
-
- shopping
-
- gaming
-
- Subscriptions
-
- Hobbies
-
- Weekend outing
-
- Expensive gadgets
Savings 20%
The last remaining 20% of your monthly salary goes into your savings as well as your investments like your emergency fund, investments like SIP’s, Gold, mutual funds, Stocks, bonds and FD’s. It’s also your safety-net as well.
The Remaining 20% of 50,000 which is 10,000 rupees goes directly towards your financial future like:
-
- Emergency fund
-
- Savings
-
- Investments
-
- Retirement funds
-
- Long term financial goals
-
- short term financial goals
-
- Debt repayment
Where Did the 50/30/20 rule Come From?
The 50/30/20 rule become widely know as a simple way to divide income between needs, wants and financial goals. it is important to budgeting guideline, not a law or a financial requirement.
There no Financial authority saying every Indian should spend exactly 50% on needs, 30% on wants and 20% on savings.
In fact, India’s own financial education material from the Reserve Bank of India (RBI) emphasizes creating an allocation based on your actual spending and financial circumstances. One RBI financial-planning guide provides an example allocation of 50% spending, 20% savings toward goals, 20% for stabilizing finances and 10% for long-term investing. It also says that people can determine the allocation formula that works for themselves and their families. A budget should be customized to your financial situation rather than followed blindly.
So the bigger lesson is: A budget should be customized to your financial situation rather than followed blindly
Does the 50/30/20 Rule Work in India?
Definitely — but not equally well for everyone
the 50/30/20 rule works in India as a flexible baseline, but it often requires adjustment due to high living costs in metro areas, heavy family obligations, and high EMI burdens.
This rule can be useful in India because it gives beginners a simple structure for thinking about their money. However, Indian households can have very different financial situations.
For example, consider two people:
Person A
Monthly income: ₹30,000
Rent: ₹12,000
Food and groceries: ₹6,000
Transportation: ₹3,000
Utilities: ₹2,000
Essential expenses are already around ₹23,000.
That is more than 75% of the person’s income.
Trying to force these expenses into a 50% limit may be unrealistic.
Person B
Monthly income: ₹1,00,000
Rent: ₹20,000
Food: ₹10,000
Transportation: ₹5,000
Utilities and other essentials: ₹5,000
This person may have significantly more flexibility to save and invest.
The same 50/30/20 structure therefore cannot be expected to work identically for both people.
Why It Can Be Hard to Apply in India?
There are several reasons why following the rule exactly may be challenging.
1. Housing Costs Can Be High
Housing is often one of the largest monthly expenses. Someone living in a major city may spend a substantial percentage of their income on rent. If rent alone consumes 35–40% of take-home income, keeping total needs below 50% becomes difficult.
2. Family Responsibilities
In India, financial responsibilities can extend beyond an individual’s personal expenses.
Someone may contribute toward:
-
- Parents’ expenses
-
- Children’s education
-
- Medical expenses
-
- Family emergencies
-
- Household bills
-
- Family loans
These expenses can make the traditional 50% needs target unrealistic.
3. EMIs Can Change the Calculation
Many Indian households have loans for:
-
- Homes
-
- Vehicles
-
- Education
-
- Personal expenses
-
- Other purchases
Loan payments can consume a significant portion of monthly income.
A person with a large EMI may need to temporarily use a different budget structure.
4. Income Levels Are Different
A fixed percentage can feel very different at different income levels.
For example:
20% of ₹25,000 = ₹5,000
20% of ₹1,00,000 = ₹20,000
Both are 20%, but the financial impact is completely different. Therefore, percentages should always be considered alongside actual income and expenses.
A Better Way to Use the 50/30/20 Rule in India
Instead of asking: Can I follow 50/30/20 exactly?
A better question is: Can I use 50/30/20 as a starting point and adjust it according to my financial situation?
For many people, this is a more practical approach.
For example, someone with high essential expenses could use:
60/20/20
60% Needs
20% Wants
20% Savings
Someone trying to save aggressively might use:
50/20/30
50% Needs
20% Wants
30% Savings and investments
Someone with very high financial responsibilities might temporarily use:
70/10/20
70% Needs
10% Wants
20% Savings
These are not official formulas. They are examples of how a budgeting framework can be adjusted.
50/30/20 Rule Example for an Indian Salary
Let’s take a hypothetical take-home salary of ₹60,000 per month.
Traditional 50/30/20 allocation
Needs: ₹30,000
Possible expenses:
-
- Rent: ₹15,000
-
- Groceries: ₹6,000
-
- Electricity and utilities: ₹3,000
-
- Transportation: ₹3,000
-
- Basic insurance/medical: ₹3,000
Wants: ₹18,000
Possible expenses:
-
- Eating out: ₹4,000
-
- Entertainment: ₹2,000
-
- Shopping: ₹4,000
-
- Subscriptions: ₹1,000
-
- Travel/hobbies: ₹4,000
-
- Miscellaneous wants: ₹3,000
Savings & financial goals — ₹12,000
Possible allocation:
-
- Emergency fund: ₹4,000
-
- Long-term investment: ₹5,000
-
- Short-term goal: ₹3,000
This is only an illustration. Your actual numbers should depend on your income, expenses and financial goals.