In my perspective, in the year 2026 choosing the right investment option can be difficult, especially when you want your money to grow while also protecting your savings. In India, Fixed Deposits (FDs) and Mutual Funds (MFs) are two popular investment choices. However, they work very differently in terms of risk, returns, liquidity and taxation.
Investors are increasingly comparing Fixed Deposits (FDs) with Mutual Funds (MFs) because interest-rate movements and changing market conditions can affect the returns they receive. So, where should you put your money? The answer depends on your financial goals, risk tolerance and investment period.
What Is a Fixed Deposit?
Fixed Deposit is known as an FD, is an investment offered by large, medium and small banks and financial institutions where you deposit a specific amount of money for a predetermined period at a fixed interest rate.
The biggest advantages of an FD is predictability. You generally know the interest rate and maturity amount when you invest. This makes FDs attractive to conservative investors who prioritize stability over higher potential returns.
Fixed Deposit (FDs) can be suitable for emergency savings, short- to medium-term financial goals and investors who do not want to take market-related risks. However, the interest earned on an FD is taxable according to the applicable income-tax rules.
What Are Mutual Funds?
A mutual fund is a managed investment vehicle that pools money from many investors to purchase a diversified portfolio of securities, such as stocks, bonds, or short-term debt.
When you buy a share or unit in a mutual fund, you own a small fraction of all the investments within that pool. This provides individual investors with built-in diversification, spreading risk across various companies and industries far more easily than buying individual stocks or bonds.
Every fund is managed by a professional portfolio manager who researches and selects the assets, aiming to match the fund’s specific financial goals (like long-term growth or regular income). Mutual funds are highly liquid, meaning you can easily buy or sell your shares at the current Net Asset Value (NAV) at the end of each trading day. They offer an accessible, hands-off way for everyday individuals to invest in the financial markets.
FD vs Mutual Funds: Which Offers Better Returns?
When you compare FD vs mutual funds, it is important to understand that FD returns are generally fixed, while mutual-fund returns are market-linked. FD is safe whereas mutual funds are risky.
For example, if you invest ₹2.5 lakhs in an FD, the interest rate determines the approximate maturity value. With an equity mutual fund, the value of your investment can rise or fall depending on market performance.
Equity investments have offered higher long-term growth potential than traditional fixed income products, but they also carry significantly higher risk. Therefore, comparing an FD’s fixed interest rate directly with a mutual fund’s expected return is not an equal comparison.
If your priority is capital stability, an FD may be more appropriate. If your objective is long-term wealth creation and you can tolerate volatility, equity mutual funds may be worth considering.
What About Taxation in 2026?
The year 2026 marks a transformative period for taxation, characterized by significant legal overhauls and restructuring aimed at administrative simplification. In India, the landmark rollout of the Income Tax Act, 2025 goes into effect on April 1, 2026, completely modernizing direct tax systems and condensing the country’s six-decade-old tax laws down to a more manageable framework. Concurrently, the United States experiences its own massive consolidation via the One Big Beautiful Bill Act (OBBBA). This sweeping U.S. legislation permanently cements the individual tax cuts originally introduced by the 2017 Tax Cuts and Jobs Act (TCJA), averting a massive scheduled sunset and providing long-term fiscal clarity for millions of households.
For individual taxpayers under India’s New Tax Regime, which serves as the default filing structure, the basic tax exemption limit is set at ₹4 lakh. Incremental tax slabs scale from 5% to 30% for incomes exceeding ₹24 lakh. Middle-class workers receive substantial relief as a standard deduction of ₹75,000, combined with an enhanced Section 87A rebate, ensures that individual income up to ₹12.75 lakh incurs an effective tax liability of zero. To promote compliance rather than severe punishment, procedural timelines have also been relaxed; individuals are now granted an extended window until March 31 to submit revised tax returns upon payment of a nominal fee.
Meanwhile, across the globe, the U.S. Internal Revenue Service (IRS) has deployed heavily adjusted thresholds for the 2026 tax year to align with macro inflation trends. Under the permanent OBBBA rules, the seven progressive federal tax brackets remain locked at 10% to 37%. For 2026, the standard deduction has climbed to $16,100 for single filers and $32,200 for married couples filing jointly. High-net-worth individual protections are also prominently expanded, as the lifetime estate and gift tax exemption threshold shifts permanently to $15 million per person ($30 million for joint filers), safeguarding multi-generational wealth transfers from reverting to previous historical minimums.
On the corporate and investment side, major revisions aim to manage domestic transparency and limit aggressive high-risk speculation. In India’s equity markets, the Securities Transaction Tax (STT) on derivatives has officially increased—rising to 0.05% on futures and 0.15% on options premium—while corporate share buybacks are now universally taxed under capital gains to protect minority shareholders. Globally, corporate tax operations are seeing an aggressive push toward digitization, with tax authorities implementing automated, rule-based systems and stricter reporting mandates for cross-border financial data, virtual assets, and foreign holdings.
Which One Is Better for Different Investors?
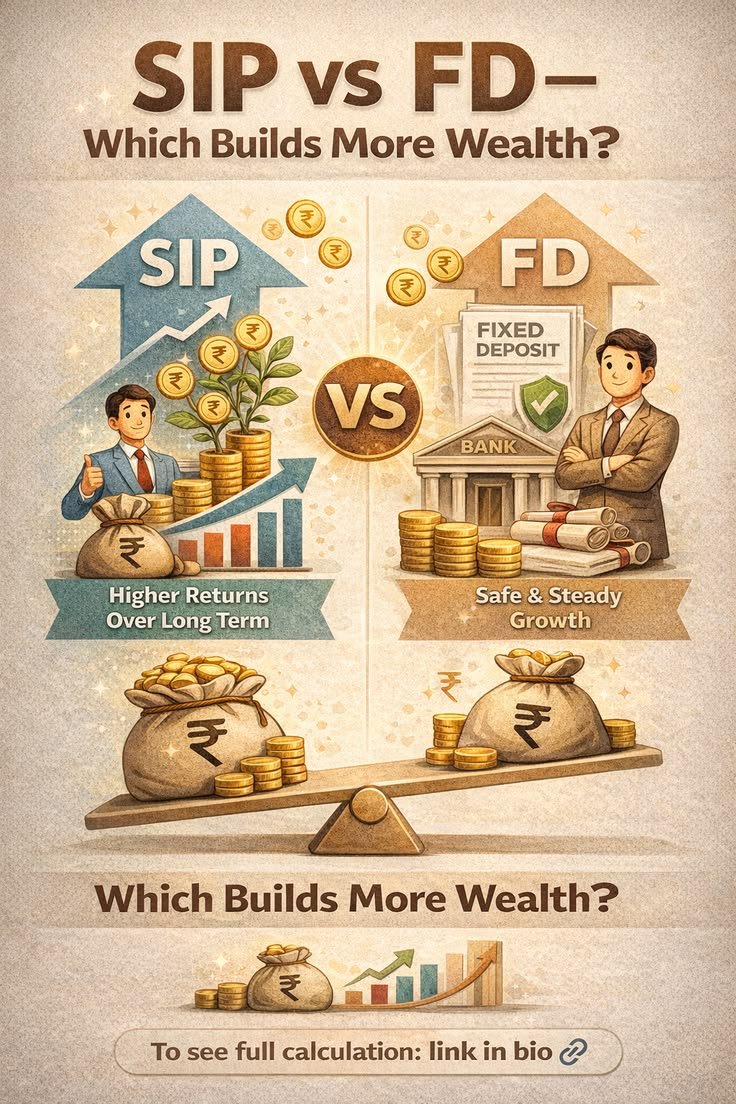
There is no single investment that is best for everyone.
An FD may be better if you:
- Prefer predictable returns.
- Have a short- or medium-term financial goal.
- Have low risk tolerance.
- Want to avoid stock-market volatility.
Mutual funds may be better if you:
- Are investing for the long term.
- Want higher potential growth.
- Can tolerate temporary losses.
- Want to build wealth through regular investments such as SIPs.
A young investor with a long investment horizon may consider allocating part of their portfolio to equity mutual funds, while keeping short-term or emergency money in safer instruments such as FDs or savings accounts.
FD or Mutual Funds: Where Should You Put Your Money in 2026?
The better question is not simply “FD or mutual funds?” but “Which investment is suitable for my goal?”
If protecting your principal and getting predictable returns are your top priorities, an FD can be a useful option. On the other hand, if you have a long investment horizon and are comfortable with market fluctuations, mutual funds can offer greater potential for wealth creation.
For many investors, a combination of different investments may make more sense than choosing single one. You could keep money required for short-term goals in safer investments while using diversified mutual funds for long-term goals.
Before investing investing some of the part of your hard earn money consider your financial goal, investment horizon, risk tolerance, liquidity requirements and taxation. Remember that mutual funds are subject to market risks, while FD returns are generally more predictable but may offer lower growth potential.
In conclusion:
FDs can provide stability, while mutual funds can provide growth potential. The right choice in 2026 depends on your personal financial situation rather than simply choosing the investment with the highest advertised return.